
A good CIBIL score can make a difference when you apply for a credit card, personal loan, car loan, or home loan in India. Lenders use your credit history to understand how responsibly you have managed borrowed money in the past.
But what happens if your CIBIL score is low? Can you improve it, and how long does it take?
The good news is that improving your credit profile is possible. It usually requires consistent repayment habits, controlled credit card spending, and regular monitoring of your credit report.
In this beginner-friendly guide, we explain how to improve CIBIL score in India, what affects your score, common mistakes to avoid, and practical steps you can start taking today.
What Is a CIBIL Score?
A CIBIL score is a three-digit number ranging from 300 to 900 that summarises your credit history. It is generated by TransUnion CIBIL using information reported by banks and other credit institutions.
Your score helps lenders assess your creditworthiness when reviewing applications for loans and credit cards.
Generally, a higher score indicates a stronger credit profile. However, having a high score does not guarantee loan approval because lenders also consider your income, existing debt, employment, and internal lending policies.
For example, two individuals earning the same monthly salary may receive different loan offers if their repayment histories and outstanding debts differ.
According to TransUnion CIBIL’s official guidance, payment history, credit utilisation, length of credit history, and credit enquiries are important factors affecting your score.
What Is Considered a Good CIBIL Score in India?
Although lenders have their own eligibility criteria, the following table provides a general way to understand CIBIL score ranges.
|
CIBIL Score |
General Interpretation |
|---|---|
| 800–900 | Excellent credit profile |
| 750–799 | Strong credit profile |
| 700–749 | Fair to good profile |
| 650–699 | May require improvement |
| 300–649 | Greater credit concerns |
These are illustrative descriptions, not official CIBIL rating categories or guaranteed lending thresholds.
A score of 750 or above is often viewed favourably, but lenders may approve or reject applications at different score levels depending on their policies.
If your score is below your target, the focus should be on improving your financial behaviour rather than trying to increase the number overnight.
How to Improve CIBIL Score: 10 Practical Tips
Improving your CIBIL score is generally a gradual process. The following steps can help you develop healthier credit habits.
1. Pay Your Credit Card Bills and EMIs on Time
Your repayment history is one of the most important factors affecting your CIBIL score.
Missing a credit card payment or loan EMI can negatively affect your credit profile, particularly when payments remain overdue.
To reduce the chances of missing a payment:
-
Set reminders before your credit card due dates.
-
Enable automatic payments where appropriate.
-
Keep enough money in your bank account for upcoming EMIs.
-
Review your payment status after each transaction.
If you are struggling to make a payment, contact your lender before the due date to discuss available options.
Practical tip: Paying the full credit card statement balance by the due date generally helps avoid interest on purchases, subject to the card’s terms. Paying only the minimum amount may avoid an immediate overdue status if paid on time, but interest can still accumulate on the remaining balance.
2. Keep Your Credit Utilisation Low
Credit utilisation is the percentage of your available revolving credit limit that you are currently using.
A high utilisation ratio can indicate greater dependence on borrowed money and may negatively affect your credit score.
Credit Utilisation Formula:
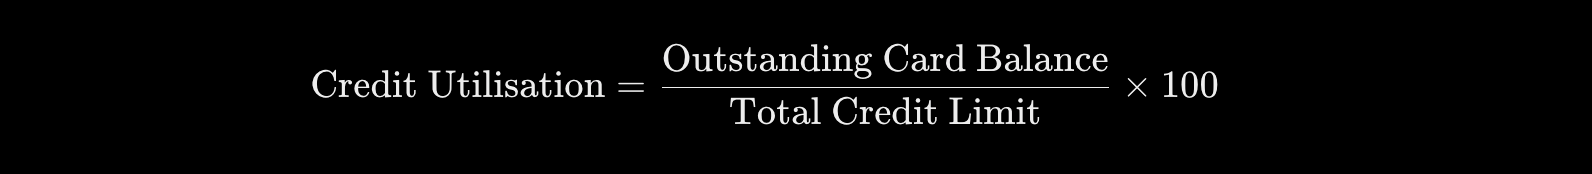
For example:
|
Particulars |
Amount |
|---|---|
| Credit card limit | ₹1,00,000 |
| Outstanding balance | ₹70,000 |
| Credit utilisation | 70% |
If you reduce the outstanding balance to ₹25,000, your utilisation becomes 25%.
Keeping utilisation below 30% is a commonly suggested guideline, but it is not an official guarantee of score improvement. Lower utilisation is generally preferable when financially practical.
Avoid spending more simply because your bank increases your credit limit.
3. Avoid Applying for Multiple Loans or Credit Cards Together
Whenever you apply for a loan or credit card, the lender may check your credit report through a hard enquiry.
Multiple hard enquiries within a short period may affect your credit score and make lenders more cautious about your borrowing behaviour.
For example, applying for five credit cards within a few weeks could create several enquiries on your report.
Instead, compare eligibility requirements and product features before applying. Submit applications only when you have a genuine borrowing need.
Checking your own CIBIL score is a soft enquiry and does not reduce your score.
4. Review Your CIBIL Report Regularly
Your CIBIL report contains detailed information about your credit accounts, outstanding balances, repayment history, and enquiries.
Sometimes, incorrect or outdated information may appear in a credit report.
Common issues to check include:
-
Loans that do not belong to you.
-
Incorrect overdue amounts.
-
Payments incorrectly reported as missed.
-
Closed loans still showing an outstanding balance.
-
Credit enquiries you do not recognise.
You can check your report through the official TransUnion CIBIL website.
Under RBI directions, eligible individuals can obtain one free full credit report, including their credit score, from each credit information company once per calendar year.
5. Dispute Incorrect Information in Your Credit Report
If you identify an error, raise a dispute with the credit bureau and, where appropriate, contact the lender that reported the information.
For example, suppose you repaid a personal loan but your report still shows an incorrect overdue balance. You should collect relevant repayment records and request verification.
Keep copies of your payment receipts, closure letters, and dispute reference numbers.
Credit bureaus generally rely on information supplied or confirmed by lenders, so legitimate corrections may require verification by the reporting institution.
Remember that accurate negative information cannot simply be deleted because it affects your score.
6. Maintain Older Credit Accounts Responsibly
The length of your credit history can influence your CIBIL score.
An older credit card with a positive repayment history may help demonstrate long-term credit management.
Closing an old card can sometimes affect your available credit limit and the characteristics of your credit history.
However, this does not mean you should keep every credit card open forever. Consider annual fees, spending habits, fraud exposure, and whether you can manage the account responsibly.
Avoid unnecessary account closures made solely in the hope of improving your score.
7. Maintain a Healthy Credit Mix
Your credit mix refers to the different types of credit accounts you have managed.
These may include:
-
Secured credit: Home loans, car loans, and certain loans backed by collateral.
-
Unsecured credit: Personal loans and credit cards.
A history of responsibly managing different types of credit may contribute positively to your overall credit profile.
However, you should never take an unnecessary loan just to improve your credit mix. Borrow only when you have a genuine financial need and a realistic repayment plan.
8. Reduce Existing Credit Card Debt
If you regularly carry large outstanding credit card balances, reducing them can improve your financial position and may support your credit score over time.
Start by listing all outstanding balances, interest rates, minimum payments, and due dates.
Consider prioritising high-interest debt while continuing to meet the required payments on other accounts.
For example, if you have two credit cards with balances of ₹40,000 and ₹20,000, reducing those balances can lower your overall credit utilisation and interest burden.
If your debt payments are difficult to manage, consider speaking with your lender about legitimate repayment arrangements before missing payments.
For better control over your expenses, read our guide on how to create a monthly budget in India.
9. Avoid Loan Settlements Where Possible
A loan or credit card account reported as settled generally means the lender accepted less than the full amount owed under a negotiated arrangement.
This is different from an account reported as closed after full repayment.
A settlement may negatively affect future credit assessments because it can indicate that the original repayment obligation was not fulfilled in full.
If you can reasonably repay your dues, doing so according to the agreed terms is generally preferable.
However, if you are experiencing serious financial hardship, a settlement may sometimes be a necessary option. Understand the consequences, request written confirmation of the arrangement, and verify how the account is reported afterward.
10. Be Patient and Build Consistent Credit Habits
There is no reliable shortcut to achieving a high CIBIL score.
Even after you repay outstanding debt, your score may not change immediately. Updates depend on when lenders report information and how the scoring model evaluates your credit history.
Focus on sustainable habits such as paying bills on time, avoiding unnecessary borrowing, reducing debt, and reviewing your credit report periodically.
Consistent behaviour matters more than checking your score every day.
How Long Does It Take to Improve Your CIBIL Score?
There is no fixed timeline for improving a CIBIL score.
Some changes, such as reducing credit card balances or correcting an error, may become visible after the relevant information is updated. Recovering from serious missed payments or defaults can take substantially longer.
The outcome depends on your starting credit profile, repayment history, outstanding debt, and other factors.
|
Situation |
What to Expect |
|---|---|
| High credit utilisation | Improvement may be possible after lower balances are reported |
| Incorrect credit report entry | Score may change after a verified correction |
| Recent missed payment | Impact may persist despite future timely payments |
| Limited credit history | Building a reliable record generally takes time |
| Multiple overdue accounts | Recovery may require sustained repayment discipline |
No company or individual can legitimately guarantee a particular score increase within a fixed number of days.
Common Mistakes That Can Affect Your CIBIL Score
Many people unintentionally damage their credit profiles through avoidable financial habits.
Some common mistakes include missing EMI due dates, paying only the minimum credit card amount every month, repeatedly applying for credit, and using nearly the entire available credit limit.
Another mistake is ignoring your credit report until you urgently need a loan.
For example, discovering an incorrect overdue entry just before applying for a home loan can create unnecessary complications.
Regular monitoring and responsible borrowing can help you identify problems earlier.
How to Check Your CIBIL Score for Free in India
You can check your CIBIL score through the official TransUnion CIBIL website.
Follow these steps:
-
Visit www.cibil.com.
-
Look for the option to access your free CIBIL score and report.
-
Complete the required registration and identity verification.
-
Access your available credit report.
-
Review your score, repayment history, account details, and enquiries.
Checking your own credit report does not lower your CIBIL score.
If you have no credit history or insufficient information for scoring, your report may display NH or NA rather than a numerical score. This does not automatically mean you have a poor credit score.
Frequently Asked Questions About CIBIL Score
1. How can I improve my CIBIL score quickly?
Start by paying overdue amounts, reducing high credit card balances, avoiding unnecessary loan applications, and checking your report for errors. These steps may help, but there is no guaranteed instant improvement.
2. Is 750 a good CIBIL score in India?
A score of 750 is generally considered strong and may support loan eligibility. However, approval depends on the lender’s policies and other factors such as income and existing obligations.
3. Does checking my CIBIL score reduce it?
No. Checking your own score is considered a soft enquiry and does not reduce your CIBIL score. Hard enquiries made by lenders during credit applications may affect it.
4. Can I improve my CIBIL score without a credit card?
Yes. Responsible repayment of eligible loans can contribute to your credit history. You do not necessarily need a credit card to build a credit profile.
5. Does paying the minimum due improve my CIBIL score?
Paying the required minimum by the due date may help you avoid being reported overdue, but it does not eliminate the remaining debt or associated interest. Carrying high balances can also affect your credit utilisation.
6. Can I get a loan with a low CIBIL score?
It may be possible, depending on the lender, your income, existing debt, collateral, and other eligibility criteria. However, a low score can limit your options or result in less favourable terms.
7. Will closing a credit card improve my CIBIL score?
Not necessarily. Closing a card may reduce your total available credit and affect your credit profile. Review the account’s fees, history, and your overall financial needs before deciding.
Conclusion
Understanding how to improve CIBIL score is an important part of managing your personal finances in India.
Your credit score reflects aspects of your borrowing and repayment history, so improving it requires responsible financial behaviour rather than shortcuts.
Start with the basics: pay your EMIs and credit card bills on time, keep credit utilisation manageable, avoid unnecessary credit applications, and check your credit report for inaccuracies.
Most importantly, borrow within your repayment capacity. A healthy credit profile should support your financial goals, not encourage additional debt.
If you are working toward better financial stability, building a realistic monthly budget and managing outstanding debt can be valuable first steps.
References
-
TransUnion CIBIL – Understanding CIBIL and Factors Affecting Your Score — Official explanation of payment history, utilisation, credit age, and enquiries.
-
TransUnion CIBIL – Frequently Asked Credit Questions — Guidance on improving credit health.
-
Reserve Bank of India – Free Annual Credit Report to Individuals — RBI directions concerning free annual credit reports.